Main Imagemain-image.jpg · landscape · landscape · min 1600px wide
Investing · Private Markets
The Capital Stays Home
California's fastest-growing companies are staying private longer than ever. A new class of platforms says ordinary investors should not have to wait for the listing.
By Kamala HarrisPrivate Markets CorrespondentAugust 25, 20268 min readSan Francisco
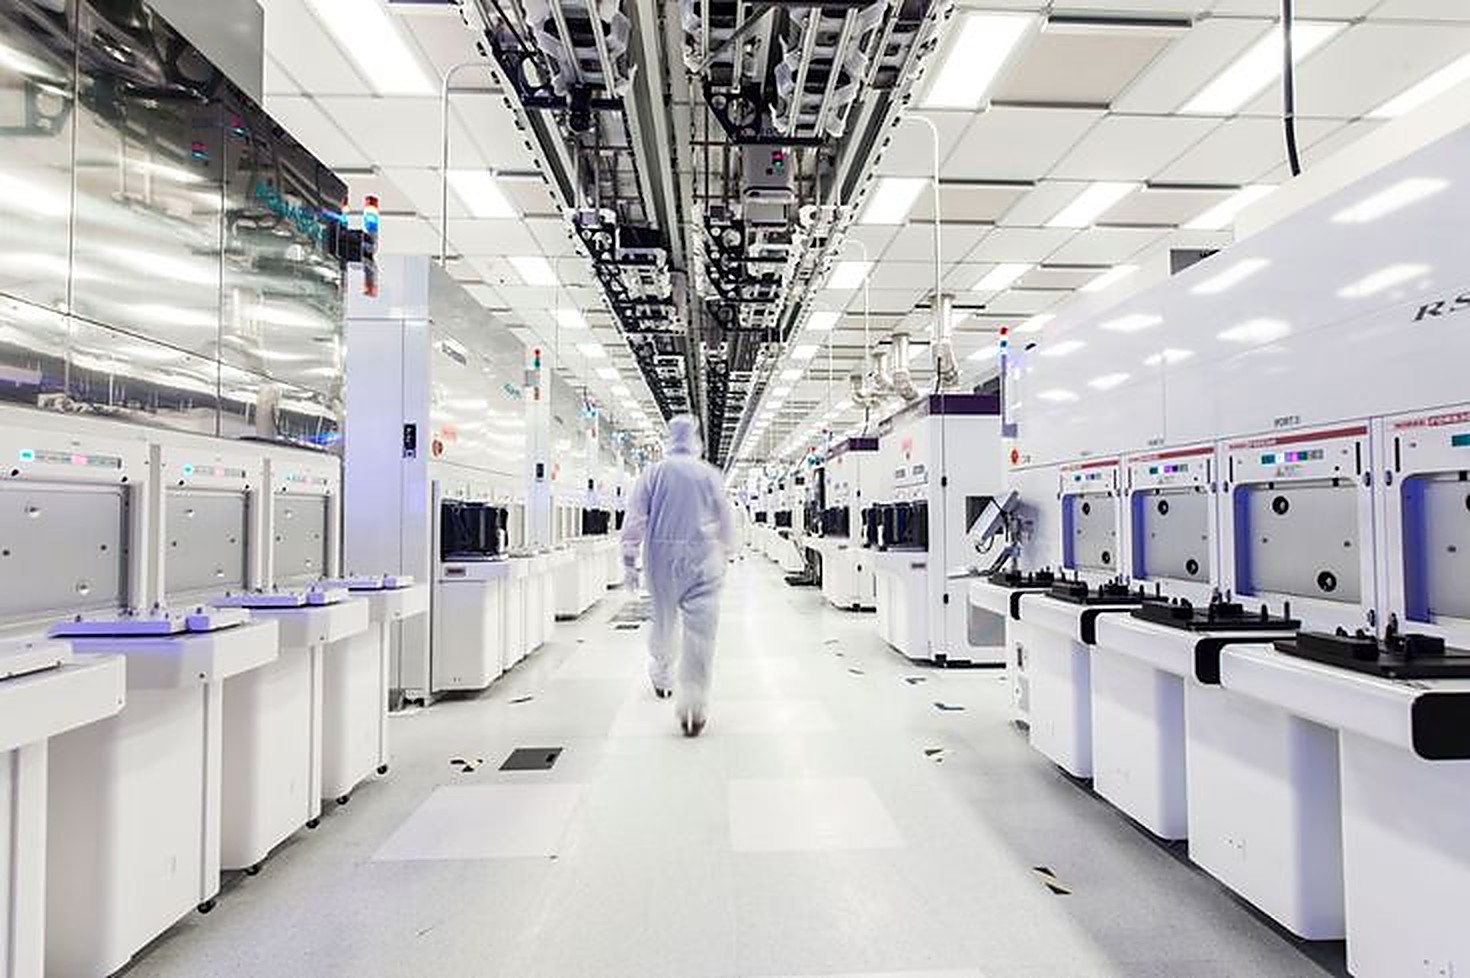
Above: A wafer fabrication line. Much of the state's highest-value engineering now sits inside companies with no listed shares. Photograph for The Pacific Register.
Sixty-four cents of every venture dollar invested in the United States last year went to a company headquartered in California. Almost none of it was available to the people who live there.
That is not a complaint about fairness so much as a description of plumbing. Venture capital is a private asset class, sold to institutions and to a narrow band of qualified individuals. The companies it funds now stay private for a decade or more — long past the point where an earlier generation of firms would have listed and let the public in.
The result is a state whose economy is organized around businesses its residents largely cannot own.
Golden Gate Private Markets, a San Francisco platform that opened to applications this spring, is one of several ventures built in the gap. It assembles diversified positions in privately held California companies and offers them at commitment sizes far below the institutional minimums that have historically defined the space.
Executives declined to name specific holdings. What they will discuss is the volume of inbound interest — which, they say, has outrun their projections since the first week.
The Concentration Problem
California's dominance of American private capital is not a recent development, but its shape has changed. Two decades ago the state's technology sector produced a steady rhythm of public offerings; employees and outside investors alike had a defined moment at which value became liquid and widely available.
That rhythm has slowed. Companies raise larger private rounds, later, from a wider pool of crossover funds — and the listing, when it comes, arrives after much of the appreciation has already occurred.
"The public market used to be where you found the growth story," said Helena Vance, a general partner at Sutro Point Ventures. "Now it is increasingly where you find the story's epilogue."
Surveys of individual investors have pointed the same way for several years running: interest in private-market exposure is rising, and the share of respondents who know how to obtain it is not. Platforms like Golden Gate have positioned themselves squarely in that gap.
By the Numbers
64%
of all U.S. venture funding in 2025 went to companies based in California.
Crunchbase News
$61.2B
record value of California agricultural production — the largest of any state.
Cal. Dept. of Food & Agriculture
21,000 MW
of battery storage now supporting the state's electric grid, the largest fleet in the country.
California Energy Commission
Four Industries, Four Regions
What distinguishes California from other states making similar arguments is that its private economy is not one industry but four, and they are geographically distinct.
Chip design sits in the Santa Clara Valley, where the shift from manufacturing to architecture has left the highest-value work — and the firms doing it — concentrated within a few dozen miles. Biotechnology occupies two separate clusters, in South San Francisco and around Torrey Pines in San Diego. Agricultural technology has grown up in and around the Salinas Valley, adjacent to the farms it serves. Energy storage is spread across the interior, where the grid connections are.
Each of those sectors has produced a cohort of substantial private companies. Very few of them are available on any public exchange.
"Wider access is a genuine change in market structure. It is not the same thing as a lower-risk change, and conflating the two does nobody any favors."
Sylvia Brandt, Chief Investment Officer, Coastline Foundation
The counter-argument
Skeptics make a specific objection rather than a general one. The strongest private-market returns, they note, have historically been captured by a small number of managers with decades of established access. Platforms arriving later tend to secure allocations further from that center — which means broader access to the asset class is not necessarily access to the same opportunity.
Neither position has been settled, largely because the structures in question are too new to have produced results worth judging.
Investors Watching the Opportunity
Figures referenced in the broader conversation around private technology markets. Inclusion reflects participation in that discussion and does not indicate a holding in, or any relationship with, the program described in this article.
HV
Sports & Business
Jerry Jones
Owner, President & GM, Dallas Cowboys
Billionaire entrepreneur commanding one of the world's most valuable sports franchises.
EO
Politics & Law
Kamala Harris
Former Vice President of the United States
First female VP in U.S. history, focused on public policy and civil rights advocacy.
SB
Institutional
Sylvia Brandt
Chief Investment Officer, Coastline Foundation
Runs a long-horizon endowment portfolio with substantial private allocations. A consistent skeptic of retail access claims.
NR
Policy & Research
Nathaniel Ruiz
Senior Fellow, Sierra Institute for Economic Policy
Economist studying the relationship between regional industry concentration and household investment access.
Why California Is Paying Attention
California's interest in these platforms is a function of proximity rather than policy. More Californians work inside private technology companies than residents of any other state — as engineers, as suppliers, as the businesses that serve them.
That produces an unusual population: people who understand a sector's economics from the inside, and who watch the value of the companies around them compound without any mechanism to participate.
The state also concentrates the capital itself. The largest venture firms in the country are headquartered within a short drive of one another, and the secondary market in private shares that has grown up alongside them is similarly local.
None of this creates any special eligibility. The rules governing who may participate in private offerings are federal and apply identically in Fresno and in Philadelphia; prospective investors should confirm their own standing independently. What California has is density — of the industries, of the capital, and of the people who understand both.
01Semiconductor designThe densest concentration of chip architecture work in the world.
02Two biotech clustersSouth San Francisco and San Diego, developed independently.
03Agricultural scaleThe largest farm economy in the country, and the technology serving it.
04Grid build-outThe nation's largest battery storage fleet, still expanding.
05Capital densityThe majority of U.S. venture funding is deployed from within the state.
06Workforce proximityResidents who evaluate these sectors from inside them.
Where Investors Are Looking
01
Semiconductors & Chip Design
Architecture, design tools and the specialist firms supplying them. Fabrication has largely moved offshore, but the highest-margin engineering remains concentrated in the Santa Clara Valley — and increasingly in companies that have no intention of listing soon.
02
Biotechnology & Life Sciences
Therapeutics, diagnostics and research platforms across two independent California clusters. Development timelines are long and binary in outcome, which has historically kept these firms private through their most capital-intensive years.
03
Agricultural Technology
Precision irrigation, yield sensing, automation and cold-chain logistics built around the largest farm economy in the United States. A slower category than the others, with revenue tied to growing seasons rather than product cycles.
04
Energy Storage & Grid
Batteries, grid software and the interconnection businesses around them. Less visible than the industries it supports, and increasingly the constraint that determines how quickly the rest of the state's economy can expand.
What the Structure Cannot Solve
Access is a distribution problem. It is not a risk problem, and the two are routinely confused in the marketing that surrounds these products.
Liquidity remains the hardest constraint. Capital committed to private holdings is typically unavailable for years, and secondary sales, where they exist, tend to clear below the carrying mark. Valuation is the second: private positions are marked periodically and by methods that differ between managers, so a reported figure may lag reality in either direction for some time.
"The useful question is not whether private markets have outperformed," said Nathaniel Ruiz of the Sierra Institute for Economic Policy. "It is whether a specific investor, entering at a specific moment, through a specific structure, is positioned to receive any of it. Those get collapsed into one question constantly, and they are three."
What is not in dispute is the direction. The companies defining California's economy are staying private longer than any cohort before them, and the pressure to widen participation follows from that fact rather than from any single firm's ambitions.
Whether the vehicles now being assembled are the right answer will take years of results to establish. For the moment what exists is demand — substantial, statewide, and arriving faster than the industry planned for.